- 5 min
FCNR Deposit Explained: Meaning, Rates, Taxation & Benefits
Written by
Kashish Manjani
- Blog
- Financial Planning
Date
16 july 2026
YouTube
If you’re an NRI looking for a safe and tax-efficient way to grow your overseas savings in India, an FCNR deposit could be the right investment option. But before investing, it’s important to understand what an FCNR deposit is, its features, interest rates, and tax implications. Many NRIs also have questions such as “What is FCNR?”, “What is the FCNR full form?”, and “Is FCNR interest taxable in the US?” Understanding these aspects can help you make informed financial decisions and avoid unexpected tax liabilities. In this guide, we’ll explain everything you need to know about FCNR deposits, including their benefits, eligibility, interest rates, taxation in India and the US, and how they compare with NRE and NRO deposits. This comprehensive guide will help you determine whether an FCNR deposit aligns with your financial goals and cross-border banking needs.
What is an FCNR Deposit?
If you’ve ever wondered “what is FCNR deposit?”, it is a special type of fixed deposit account designed exclusively for Non-Resident Indians (NRIs). An FCNR deposit allows NRIs to deposit their money in designated foreign currencies instead of Indian Rupees, helping protect their savings from exchange rate fluctuations.
Unlike traditional fixed deposits, the principal amount and the interest earned are maintained in the same foreign currency, making FCNR deposits an attractive investment option for NRIs who earn or hold funds overseas.
Key Features of an FCNR Deposit
- Available only to NRIs and Persons of Indian Origin (PIOs).
- Deposits are maintained in approved foreign currencies such as USD, GBP, EUR, AUD, CAD, JPY, and others permitted by the Reserve Bank of India (RBI).
- Offers protection against currency exchange risk.
- Earns fixed interest over the chosen tenure.
- Both the principal and interest are fully repatriable, subject to applicable regulations.
Quick Answer: An FCNR deposit is a foreign currency fixed deposit account that enables NRIs to earn interest while protecting their investments from currency fluctuations.
FCNR Full Form
The FCNR full form is Foreign Currency Non-Resident Deposit.
It is a term deposit account offered by authorised Indian banks specifically for NRIs who wish to hold their deposits in foreign currency instead of Indian Rupees.
Since the deposit remains in the selected foreign currency throughout its tenure, investors are protected from fluctuations in the value of the Indian Rupee.
Who Can Open an FCNR Deposit?
An FCNR deposit can be opened by individuals who meet the eligibility criteria prescribed by the Reserve Bank of India.
You can open an FCNR deposit if you are:
- A Non-Resident Indian (NRI).
- A Person of Indian Origin (PIO), as permitted under RBI guidelines.
Before opening an FCNR deposit, keep in mind:
- The deposit must be maintained in one of the approved foreign currencies.
- The account can be opened with authorised banks in India that offer FCNR deposit facilities.
- The deposit is available for fixed tenures as specified by the bank and RBI regulations.
Did You Know?
An FCNR deposit is particularly suitable for NRIs who wish to preserve their savings in foreign currency while earning fixed returns without worrying about exchange rate volatility.
Features of FCNR Deposits
An FCNR deposit is designed to help NRIs grow their foreign currency savings while protecting them from exchange rate fluctuations. Here are the key features that make it a preferred investment option:
- Held in Foreign Currency: Deposits are maintained in designated foreign currencies such as USD, GBP, EUR, AUD, CAD, JPY, and others permitted by the Reserve Bank of India (RBI).
- Protection Against Exchange Rate Risk: Since both the principal and interest remain in the same foreign currency, you are protected from fluctuations in the Indian Rupee.
- Fixed Deposit Tenure: FCNR deposits are available for tenures ranging from 1 year to 5 years, depending on RBI guidelines and the bank’s offerings.
- Competitive Interest Rates: Interest rates vary across banks, the chosen currency, and the deposit tenure.
- Principal and Interest Are Repatriable: Both the deposit amount and the interest earned can generally be transferred overseas, subject to applicable regulations.
- Loan Facility: Many banks allow deposit holders to avail loans against their FCNR deposits, subject to their terms and conditions.
- Available Only to Eligible NRIs: FCNR deposits can be opened only by eligible Non-Resident Indians (NRIs) and other eligible persons as permitted under RBI regulations.
Quick Tip: If your primary objective is to protect your overseas savings from currency fluctuations while earning fixed returns, an FCNR deposit can be a suitable option.
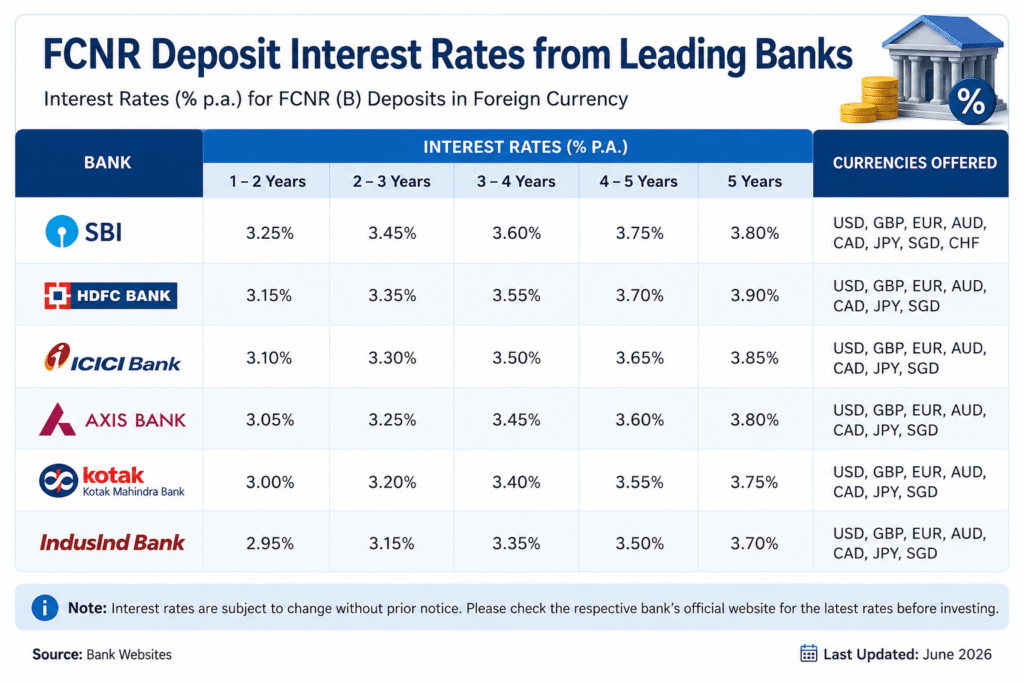
FCNR Deposit Interest Rates
One of the biggest factors investors consider before opening an FCNR deposit is the interest rate. FCNR deposit interest rates are not fixed across all banks—they vary based on the bank, the foreign currency chosen, and the deposit tenure. Banks determine these rates within the framework prescribed by the Reserve Bank of India (RBI).
Factors That Influence FCNR Deposit Interest Rates
- The bank offering the deposit
- The foreign currency selected (USD, GBP, EUR, AUD, etc.)
- The deposit tenure
- Prevailing international interest rate environment
- RBI guidelines applicable to FCNR(B) deposits
Things to Keep in Mind
- Compare interest rates offered by different banks before investing.
- Higher interest rates should be evaluated along with the bank’s service quality and deposit terms.
- Interest rates are subject to change and may differ across currencies and tenures.
Note: Always check the latest FCNR deposit interest rates on your bank’s official website before investing, as rates are revised periodically.
FCNR Deposit Taxation
Tax on FCNR Deposits in India
The tax on FCNR deposits in India depends primarily on your residential status under the Income-tax Act.- Interest earned on FCNR deposits is generally exempt from income tax in India while you qualify as a Non-Resident Indian (NRI).
- Your tax treatment may change if your residential status changes after returning to India. Therefore, it is advisable to review your FCNR deposits as part of your overall financial and tax planning.
Is FCNR Interest Taxable in the US?
A common question among NRIs is “Is FCNR interest taxable in the US?” If you are a US tax resident or US taxpayer, the interest earned on your FCNR deposit may be subject to US tax reporting and taxation, even if it is exempt from tax in India. The applicable treatment depends on your tax residency, reporting obligations, and the tax laws of the United States.| Scenario | Taxability |
|---|---|
| Tax on FCNR Deposits in India | Usually exempt for NRIs |
| Interest after becoming Resident | Taxable |
| RNOR Status | Depends on residential status |
| US Residents | May have US tax reporting obligations |
Need Help with FCNR Tax Planning?
Get expert guidance on FCNR deposits, taxation, and cross-border financial planning.
Is FCNR Interest Taxable in India?
Whether FCNR interest is taxable in India depends on your residential status under the Income-tax Act.
- If you qualify as a Non-Resident Indian (NRI) under Indian tax laws, the interest earned on your FCNR deposit is generally exempt from income tax in India.
- This tax exemption makes FCNR deposits a preferred investment option for many NRIs looking to earn tax-efficient returns on their foreign currency savings.
- However, if your residential status changes after returning to India, the tax treatment of your FCNR deposit may also change.
- Since taxation depends on your residential status and individual circumstances, it is advisable to review your deposits before relocating to India.
Note: The tax on FCNR deposits in India is governed by the provisions of the Income-tax Act and may vary based on your tax residency.
Is FCNR Interest Taxable in the US?
Many NRIs living in the United States frequently ask, “Is FCNR interest taxable in the US?”
The answer depends on your US tax residency and reporting requirements.
- If you are considered a US tax resident, the interest earned on your FCNR deposit may be taxable in the United States, even if it is exempt from tax in India.
- In addition to taxation, you may also have reporting obligations for your foreign financial accounts and overseas income under applicable US tax laws.
- Since the tax treatment can vary depending on your individual circumstances, it is important to understand your cross-border tax obligations before investing.
Important: If you have financial interests in both India and the US, consult a qualified tax professional to understand your tax reporting and compliance requirements.
FCNR vs NRE vs NRO Deposit
NRIs often compare FCNR, NRE, and NRO deposits before deciding where to invest their savings. While all three accounts are designed for NRIs, they differ in terms of currency, taxation, repatriation, and purpose.
| Feature | FCNR Deposit | NRE Deposit | NRO Deposit |
|---|---|---|---|
| Currency | Foreign Currency | Indian Rupees (INR) | Indian Rupees (INR) |
| Exchange Rate Risk | No | Yes | Yes |
| Who Can Open | NRIs | NRIs | NRIs |
| Principal & Interest Repatriation | Fully Repatriable | Fully Repatriable | Subject to applicable regulations |
| Tax on Interest in India | Generally exempt for eligible NRIs | Generally exempt for eligible NRIs | Generally taxable in India |
| Primary Purpose | Hold overseas earnings in foreign currency | Park foreign income in INR | Manage income earned in India |
Which Deposit Should You Choose?
The right option depends on your financial goals and the source of your funds:
- Choose an FCNR deposit if you want to keep your savings in foreign currency and avoid exchange rate fluctuations.
- Choose an NRE deposit if you want to maintain your overseas earnings in Indian Rupees with repatriation benefits.
- Choose an NRO deposit if you need to manage income earned in India, such as rent, pension, or dividends.
Expert Tip: Rather than choosing one account over another, many NRIs use a combination of FCNR, NRE, and NRO accounts to manage different financial needs efficiently.
Advantages & Disadvantages of FCNR Deposits
Like any investment option, an FCNR deposit comes with its own set of benefits and limitations. Understanding both can help you decide whether it aligns with your financial goals.
Advantages of FCNR Deposits
- Protection Against Exchange Rate Risk: Since the deposit is maintained in foreign currency, you are protected from fluctuations in the Indian Rupee.
- Tax Benefits for Eligible NRIs: Interest earned on FCNR deposits is generally exempt from income tax in India while you qualify as an NRI.
- Fully Repatriable: Both the principal amount and the interest earned can generally be repatriated abroad, subject to applicable regulations.
- Fixed Returns: FCNR deposits offer predictable returns over the chosen deposit tenure.
- Multiple Currency Options: Deposits can be opened in various approved foreign currencies, allowing you to invest in the currency you earn.
Disadvantages of FCNR Deposits
- Available Only to NRIs: Resident Indians are not eligible to open FCNR deposits.
- Interest Rates May Vary: Returns depend on the chosen currency, tenure, and the bank’s prevailing interest rates.
- Tax Implications May Change: The taxation of FCNR deposits may change if your residential status changes after returning to India.
- Foreign Tax Obligations: Depending on your country of residence, such as the United States, interest earned on FCNR deposits may be subject to local tax reporting and taxation.
Make Your NRI Investments Work Smarter
Get personalized, fee-only financial advice tailored to your investment goals.
Written by
Kashish Manjani
Kashish blends strategic thinking with timeless financial principles — helping clients grow, protect, and align their wealth with their values. Kashish blends strategic thinking with timeless financial principles — helping clients grow, protect, and align their wealth with their values.
FAQs
Frequently Asked questions
1. What is an FCNR deposit?
An FCNR (Foreign Currency Non-Resident) Deposit is a fixed deposit account that allows NRIs to hold their savings in designated foreign currencies while earning interest and protecting their funds from exchange rate fluctuations.
2. What is the FCNR full form?
The FCNR full form is Foreign Currency Non-Resident Deposit.
3. Who is eligible to open an FCNR deposit?
FCNR deposits can generally be opened by Non-Resident Indians (NRIs) and eligible Persons of Indian Origin (PIOs) in accordance with RBI guidelines.
4. Is FCNR interest taxable in India?
Interest earned on an FCNR deposit is generally exempt from income tax in India while you qualify as an NRI. However, the tax treatment may change if your residential status changes.
5. Is FCNR interest taxable in the US?
If you are a US tax resident, the interest earned on your FCNR deposit may be taxable in the United States and may also be subject to applicable reporting requirements under US tax laws.
6. What is FCNR deposit taxation?
FCNR deposit taxation depends on your residential status and the tax laws applicable in your country of residence. While the interest is generally exempt from tax in India for eligible NRIs, overseas tax obligations may still apply.
7. What is the tenure of an FCNR deposit?
FCNR deposits are generally available for tenures ranging from 1 year to 5 years, subject to RBI guidelines and the policies of individual banks.
8. Which currencies are available for FCNR deposits?
FCNR deposits can be opened in approved foreign currencies such as USD, GBP, EUR, AUD, CAD, JPY, and other currencies permitted by the Reserve Bank of India.
9. Can I prematurely withdraw an FCNR deposit?
Most banks allow premature withdrawal of FCNR deposits, although it may be subject to the bank’s terms, conditions, and applicable penalties.
10. How do I choose between an FCNR, NRE, and NRO deposit?
The right choice depends on your financial goals, source of income, currency preference, and repatriation requirements. Understanding the differences between these accounts can help you select the most suitable option for managing your NRI finances.