High Income, No Wealth? Why Chasing What’s Hot isn’t an Asset Allocation
Written by
Kashish Manjani
- Blog
- Investment
Date
17 November 2026
YouTube
I meet this household almost every month.
Two good incomes and a healthy surplus every month. No big loans. Ten years into their careers, the net worth is a fraction of what that surplus should have built.
When we go through their statements, the money hasn’t been wasted. It has been busy:
- A few IPOs, because everyone at work was applying.
- A small-cap fund, bought after it had doubled.
- Some options trading, because a friend made money in it.
- A little crypto. Some silver, after it was all over the news.
- A savings account holding whatever was left.
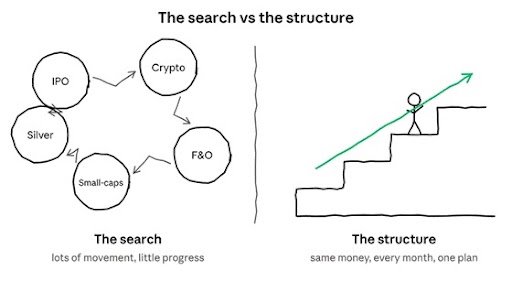
Each decision made sense on the day. Put together, they aren’t a plan. When whatever is hot becomes your asset allocation, you don’t have an asset allocation. You have a search for the next big thing. That search is the most common reason I see good income fail to become wealth.
The scorecard of the search
This isn’t my opinion. The regulator and the fund houses have measured it:
| What gets chased | What the data shows | Source |
|---|---|---|
| Futures & options | 87.7% of individual traders lost money in FY26, a combined ₹91,685 crore. Over FY22–24, 93% lost. | SEBI, Aug 2026 |
| IPOs | Individual investors sold about half their allotted shares within a week of listing, and 70% within a year. | SEBI, Sep 2024 |
| IPOs, held on | Of 374 issues listed from July 2020 to January 2026, 180 trade below their issue price. | Axis Capital via Open |
| The next multibagger | Across 3,967 Indian stocks (1990–2020), the median stock lost 33.6% over its listed life. Only 38% made money at all. | Bessembinder et al., via DSP Netra |
| Last year’s winner | Silver rose 98% in the year to July 2026. Silver ETF investors made about 18%, and 56% of the money put in that year was at a loss. | DSP Netra, Sep 2026 |
Look at the last row closely. Silver wasn’t a bad asset; it had a brilliant year. The money simply arrived after the move. That is the real cost of chasing: you buy the right thing at the wrong time.
The fund made money. The investor didn't.
The same pattern shows up inside ordinary mutual funds. Here is what four “hot” categories returned, against what the money that flowed into them actually earned:
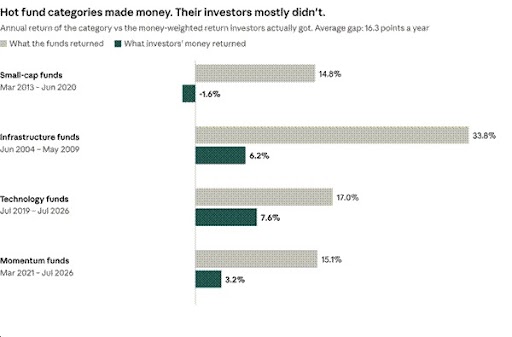
Small-cap funds compounded at 14.8% a year from 2013 to 2020. Investors’ money in them made −1.6%, because it poured in after the good years and ran out during the bad ones. None of these funds were bad. The gap between the fund’s return and the investor’s return is behaviour, and it is often bigger than any difference between a good fund and a great one.
What the search actually costs you
The gap looks small in a single year. Over a career, it isn’t. Take a household that can put away ₹1 lakh a month:
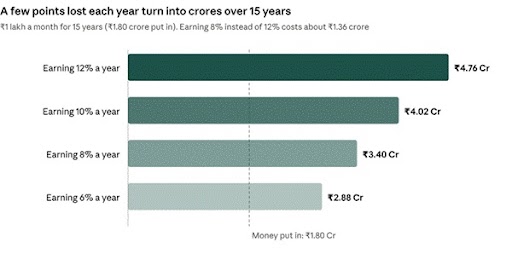
The difference between a disciplined 12% and a distracted 8% is about the price of a house. And nothing dramatic has to go wrong to lose those four points. A few late entries, a few panicked exits and a few years of idle cash are enough.
What good advice is actually worth
Vanguard has tried to put a number on this. Its “Adviser’s Alpha” research, run across the US, UK, Europe, Australia and Canada, estimates that following good advice practices can add about 3% in net returns. Where that value comes from is the interesting part:
| What an advisor does | Value Vanguard estimates |
|---|---|
| Behavioural coaching: keeping you invested in bad years, stopping you chasing in good ones | About 1.5%, the single largest piece |
| Rebalancing back to your plan | About 0.3–0.9% |
| Lower-cost implementation | About 0.3–0.7% |
| Choosing the right asset allocation | Significant, but too personal to put one number on |
The biggest contributor isn't picking funds. It's behaviour.
Another study found the same thing from the other side. Of 58,168 self-directed investors, those who made even one change to their portfolio over five years gave up between 1.04% and 1.5% a year, compared with simply holding (Weber, 2013, cited by Vanguard).
Vanguard is clear that this value doesn’t arrive evenly each year. It shows up in bursts, in the moments of panic or euphoria when people are most tempted to abandon the plan. Those are exactly the moments in the scorecard above.
This research covers developed markets, not India, and describes advice in general, not any one firm. It is not a promise of returns.
How wealthy families think differently
After years of sitting across the table from both kinds of families, I see one difference more than any other. It isn’t income, and it isn’t intelligence. It’s the order in which they do things.
| Families who build lasting wealth | Most well-earning households | |
|---|---|---|
| The first question | “What is the plan for this money?” | “What’s doing well right now?” |
| What comes first | Structure, then products | Products, and the structure never comes |
| When they take advice | Before they invest | After a loss |
| How allocation is decided | Written down in advance, reviewed on a schedule | Whatever the news, a colleague or a WhatsApp group suggests |
| A hot opportunity | Fits it into a small box, if at all | Moves the whole portfolio towards it |
| How they judge success | Against their own goals | Against someone else’s best trade |
Wealthy families don’t usually have better tips. They have a structure first and stick to it. Most of us were never taught to work that way. We were taught to save, then left to pick from whatever was being sold that year. The good news is that structure isn’t reserved for the rich. Anyone with a monthly surplus can build one.
Structure beats search
Here is what working structure-first looks like in practice:
| The search | A structure | |
|---|---|---|
| Decides where money goes | Whatever is in the news | Your goals and their deadlines |
| Asset allocation | Whatever went up last year | Set in advance, rebalanced on rules |
| When markets fall | Stop, switch or sell | Keep investing, add if surplus allows |
| When something gets hot | Buy more | Check if it’s already priced in |
| How you judge progress | Against your friend’s best trade | Against your own plan |
A simple version of that structure, before any product is picked:
| Bucket | What it’s for | Where it goes |
|---|---|---|
| Emergency fund | 6 months of expenses | Savings and liquid funds. Never the market. |
| Money needed in under 3 years | A car, a wedding, a down payment | Debt funds and deposits |
| Goals 3–7 years away | Children’s school, a sabbatical | Hybrid and multi-asset funds |
| Goals 7+ years away | Retirement, financial freedom, higher education | Diversified equity, with some gold as a hedge |
| Explore money (optional) | IPOs, themes, crypto, that tip from a friend | No more than about 5% of your portfolio |
The last row matters. Telling people never to try anything new doesn’t work. Giving the urge a small box does. If a hot idea works, it’s a bonus. If it goes to zero, nothing in your plan breaks.
An advisor’s job is to build this structure with you, attach real numbers to each goal, and hold you to it in the months when the search looks more exciting.
The short version
Wealth is rarely built by finding the one great idea. It is built by putting a large surplus into a sensible structure every month, and leaving it there long enough to compound.
If your income is healthy but your net worth isn’t keeping up, the market is probably not the problem. The missing structure is. A planning conversation is the place to start.
Good income, but the net worth isn't keeping up?
We’ll map every rupee you have to a goal and a deadline
Written by
Kashish Manjani
Kashish Manjani
CFP®, CTEP · Co-founder, Aikeyam
Kashish co-founded Aikeyam, a fee-only SEBI Registered Investment Adviser. Over nine years of advising, including as AVP, Financial Advisory at a SEBI-registered adviser, she has worked with 400+ families across firms, many of them NRIs and returning Indians, on plans that span India and abroad.
Featured in The Economic Times | Host of Money Talks with Kashish on YouTube.
FAQs
Frequently Asked questions
Why am I not building wealth despite a good salary?
Usually it’s not the income. It’s a missing structure: money spread across whatever was popular each year, with no link to goals or deadlines. Behaviour such as late entries, panicked exits and idle cash can cost several percentage points a year without any single big mistake.
What is asset allocation, and why does it matter more than fund selection?
Asset allocation is how your money is split between equity, debt, gold and cash, based on your goals and time horizons. It drives most of a diversified portfolio’s long-term risk and return. Picking a slightly better fund matters far less than getting the split right and sticking to it.
Should I invest in IPOs, crypto or F&O?
If you want to, keep it to a small “explore” bucket of about 5% of your portfolio, so a loss can’t damage your goals. SEBI’s data shows most individual F&O traders lose money, and many IPOs trade below their issue price after the listing-day buzz fades.
What does a financial advisor actually add?
Vanguard’s research in developed markets estimates that good advice can add about 3% in net returns over time. The largest share comes from behavioural coaching: keeping you invested when it’s uncomfortable and stopping you chasing when it’s exciting. This is industry research, not a promise of returns.
What is the difference between fund returns and investor returns?
A fund’s return assumes you invested once and held throughout. Investors’ actual returns depend on when money goes in and out. When money chases recent winners, investors can earn much less than the fund itself. For example, small-cap funds returned 14.8% a year from 2013 to 2020, while investors’ money in them earned −1.6%.